San Diego · Coastal California

Fewer rooms.
A far better view.

Downsizing is not a step down. For most empty nesters it is the largest financial decision of their retirement — and it deserves a plan, not just a listing.

LPT Realty · DRE #02298792 San Diego · Imperial · Riverside Former mortgage originator — QM & Non-QM

01 — The Move

The house did its job. The question is what the equity does next.

You raised a family in four bedrooms. You are now heating, insuring, cleaning, and paying taxes on three of them for the two weeks a year the kids come home.

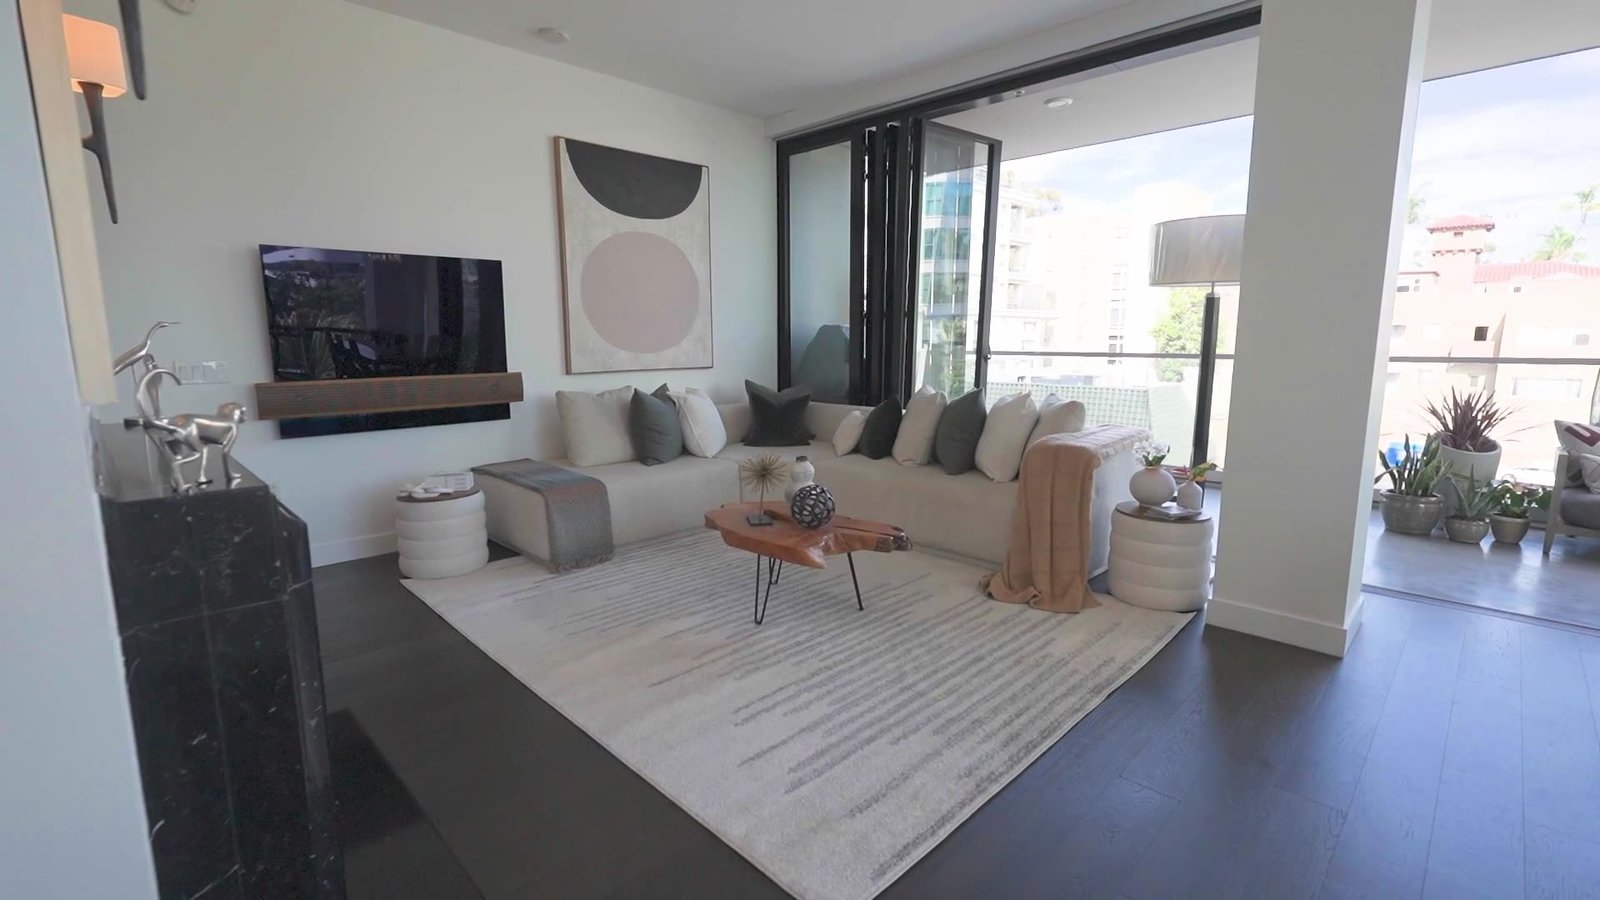
Meanwhile the single largest asset you own is sitting there, illiquid, doing nothing but appreciating quietly and costing you maintenance. Somewhere between that house and the coast is a smaller, better place — walkable, low-maintenance, with a view worth waking up to and a monthly cost that frees up the rest of your life.

Getting from here to there is where most people get stuck. Not because the market is hard, but because the sequence is: sell first or buy first, what the tax bill looks like, whether the low property tax assessment follows you, whether a lender will even talk to you now that the W-2s have stopped, and what happens to thirty years of belongings.

That sequence is the entire job. I do it in a specific order, with the numbers on the table before anything is listed or shown.

See the process

02 — The Advantage

I structured the loan before I ever listed the house.

Four years originating mortgages — conventional and Non-QM — before real estate. That background is not a line on a bio. It is the reason these moves close.

i

Financing solved before the offer

Most downsizing offers die in underwriting, not negotiation. Retirement income, asset depletion, reverse-purchase and Non-QM structures all have rules. I pressure-test the approval path first, so your offer is credible the day it is written.

ii

The sequence, modeled four ways

Sell and rent back. Sell and rent. Buy first on a bridge or HELOC. Contingent purchase. Each one has a real cost and a real risk. You see all four side by side, with your numbers, before we commit to one.

iii

Tax strategy coordinated, not assumed

Prop 19 tax-base transfers and the Section 121 gain exclusion can swing this move by six figures. I flag what applies, quantify it, and get your CPA in the room early — while it can still change the plan.

More about how I work

Bo Presnillo, REALTOR® with LPT Realty, standing in a sunlit coastal California home
Bo Presnillo REALTOR® · LPT Realty
DRE #02298792

03 — About

Straight answers, in the right order.

I spent four years on the lending side of the table, originating both conventional and Non-QM loans, and years before that in enterprise sales at AT&T, Spectrum, and Charter — rooms where the fastest way to lose the deal was to oversell it.

Both jobs taught the same lesson. People do not need to be persuaded. They need the constraints laid out plainly, the tradeoffs quantified, and someone who will say “not that one” when it isn't right.

BrokerageLPT Realty
LicenseDRE #02298792
Lending backgroundQM & Non-QM
Counties servedThree

Read the full background

05 — Free Guide

The Coastal Downsizing Guide

A plain-English walkthrough of the decision, written for San Diego homeowners 55 and over. No fluff, no listing pitch — the numbers and the sequence.

  • 01 How Prop 19 lets you carry your tax base — and the three-transfer limit
  • 02 The Section 121 exclusion, your basis, and what improvements actually count
  • 03 Sell-first vs. buy-first, with the real cost of each path
  • 04 Qualifying for a mortgage after the W-2s stop
  • 05 The 12-month downsizing timeline, week by week

Delivered to your inbox within a minute. No drip campaign you can't leave, no sharing your information, and no obligation whatsoever. Prefer to just talk?

It's on the way.

Check your inbox in the next minute — and your spam folder if it isn't there. If anything in it raises a question about your own situation, reply straight to that email. It comes to me directly.

Contact

Let's map the equity first.

A first conversation is 30 minutes, costs nothing, and ends with a one-page picture of what this move looks like in your numbers. Whether that's this year or in three.