Financing gets confirmed before you tour
Nothing wastes a year like falling for a property you cannot fund. Retired buyers routinely qualify — through asset-depletion programs, pension and Social Security income, or Non-QM products that underwrite assets instead of employment — but each of those has rules, and the time to find out which applies is before, not after.
Having originated these loans myself, I get that conversation started with a lender at the outset. It also makes your offer credible: listing agents can tell the difference between a form letter and a file someone has actually reviewed.
The HOA is the purchase
On a condo or a high-rise you are not only buying a unit. You are buying into an association, its reserves, its governance, and its future assessments. This is where I spend the most diligence time, and where I most often tell a client to walk away from something they have already fallen for.
- The reserve study. An underfunded reserve is a special assessment with a date on it, not a saving. Low dues can be the warning sign rather than the bargain.
- Assessment history. What has been levied, how often, and how large.
- Board minutes. Several years of them. Litigation, deferred maintenance, and governance quality all show up here long before they show up in a disclosure packet.
- What the dues actually cover. Compared against what you currently spend maintaining a detached home — not against zero.
Filtering for the life, not the listing
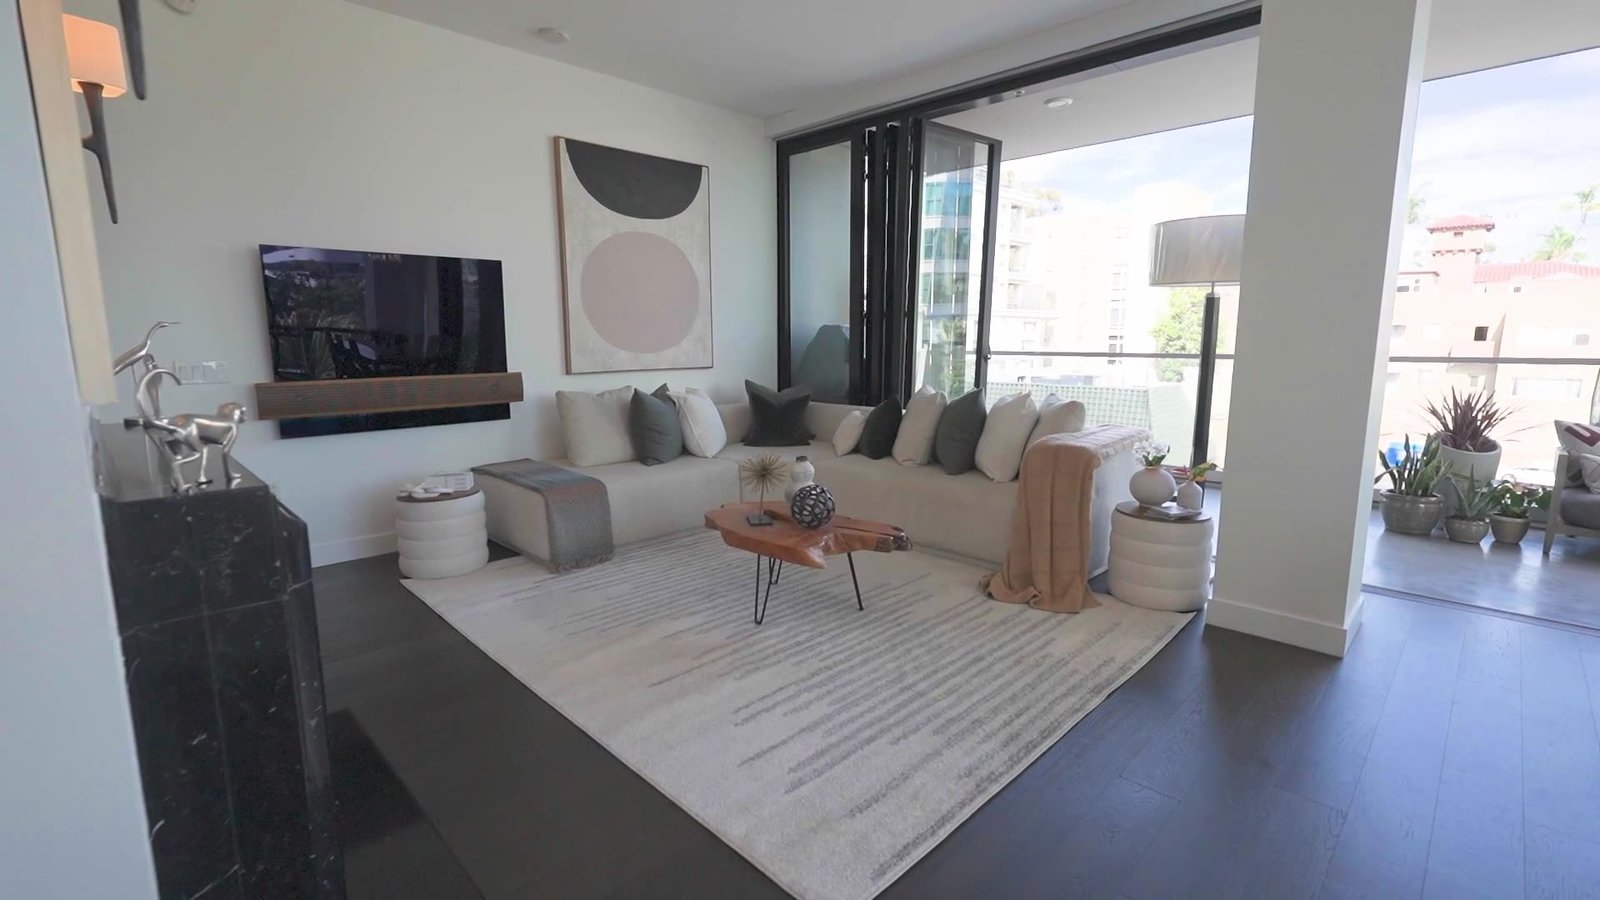
Search criteria for a downsizing buyer look nothing like a family's. Single-level or a reliable elevator. Step-free access from the parking space, not just from the front door. Primary bedroom on the entry level. Doorway widths if that is a consideration now or plausibly later. Proximity to the medical care you actually use.
These belong in the search from day one rather than as a disappointment discovered on the third tour. I would rather have the frank conversation early.
Off-market and pre-MLS
In thin coastal inventory the right property sometimes never reaches the open market. Brokerage networks and agent relationships are how you hear about it first — and in areas like Encinitas and Coronado, where the right floor plan may surface twice a year, that access is the difference between buying and waiting.
The replacement-property purchase has to be coordinated with the sale for the tax-base transfer to work. The rules have deadlines, and the sequence matters. This is why the buying and selling sides of a downsizing move cannot be run as two separate transactions by two separate people.